Let’s Connect
Get a Platform Assessment
Get a Platform Assessment
Perth’s NBFCs, asset finance providers, and non-bank lenders serve a Western Australian market shaped by commercial, equipment, and asset finance demand and by resources-linked income patterns. To serve that market well, lenders need technology that makes lending faster, more connected, and easier to scale.
Digital lending solutions connect origination, underwriting, servicing, payments, and analytics into one streamlined lending lifecycle. This helps Perth lenders reduce manual processing, accelerate credit decisions, improve the borrower experience, and gain real-time visibility into portfolio performance.
For lenders with legacy systems, Sigma Infosolutions modernises lending workflows, connects core financial systems, and supports evolving compliance requirements through digital lending solutions built around your products, policies, and technology environment.
Digital lending software development involves designing the technology and workflows behind a lender’s lending operations. It spans digital application journeys, borrower data capture, document management, credit decisioning, workflow orchestration, loan servicing, payments, collections, and reporting.
The platform can also connect to credit bureaus, identity verification providers, core banking systems, payment gateways, and other financial systems, creating a connected technology environment aligned to the lender’s products, policies, and processes.
Scoped in writing before we start.
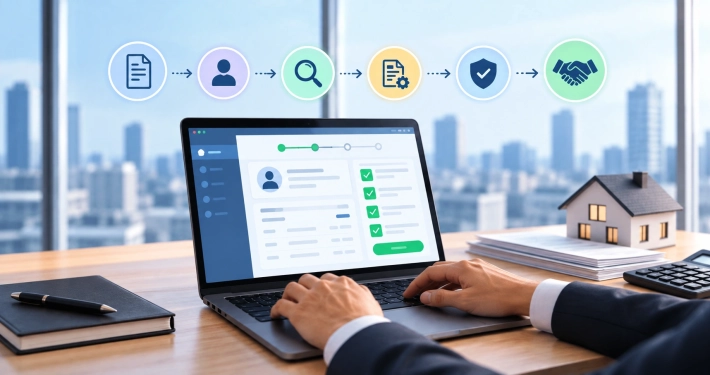
A slow application form is a lost applicant, whether that applicant is a first-home buyer or a mining services contractor financing new equipment. Sigma builds origination flows with real-time eligibility checks, document capture, and identity verification, configured around your product lines.

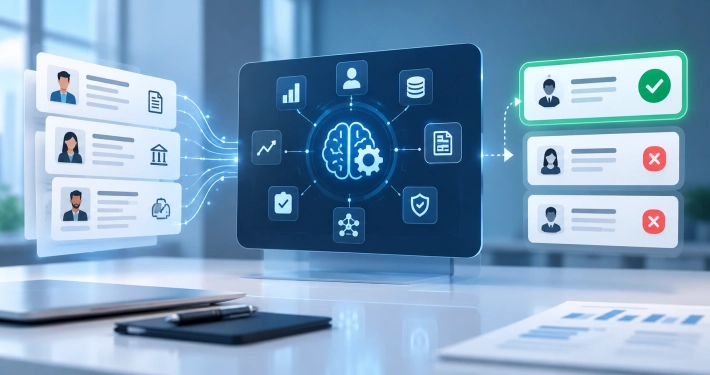
Underwriting in a resources-linked economy needs to account for cyclical income and asset-backed lending patterns that generic scoring models may not account for. Sigma builds decisioning engines that combine rules-based logic with model-driven scoring, with every decision logged and explainable.
Once a loan is funded, the operational load shifts to servicing. Sigma builds repayment scheduling, automated reminders, and delinquency workflows that reduce manual chasing without making the borrower experience feel punitive.
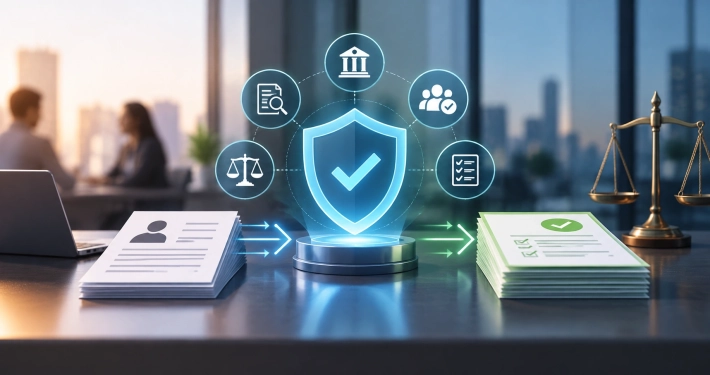
The National Consumer Credit Protection Act requires credit licensees to make reasonable inquiries, verify a borrower’s financial situation, and assess whether a loan is not unsuitable before approval. Sigma builds that assessment logic into the origination and underwriting flow, with the documentation trail ASIC’s Regulatory Guide 209 expects.
With non-bank lenders now inside the CDR regime, product and consumer data need to be shareable through standardised APIs. Sigma builds the data layer and API connections that make CDR compliance a technical non-event.
A lending platform disconnected from your core banking system, payment gateway, or CRM creates manual reconciliation work every day. Sigma connects your lending stack so data moves once and stays accurate everywhere.
Plenty of WA lenders are still running origination or servicing systems built for a smaller, simpler product range. Sigma modernises these in phases, migrating data and logic without pausing loan operations.
Portfolio health, delinquency trends, and collections performance need to be visible without a spreadsheet built every Monday, especially with income patterns tied to resources-sector cycles. Sigma builds reporting layers your credit and risk teams can act on.

ISO 9001:2015 and ISO 27001:2022 certified

Compliance logic built into the platform, not bolted on

Underwriting and analytics built with resources-linked income patterns in mind

Validated cloud security and architecture practices

Origination through servicing and analytics, under one delivery team

Based in NSW with delivery and support hours structured around AWST business hours
Four phases. Compliance built in from the start.

Understand your credit policy, regulatory obligations, and existing systems

Design origination, underwriting, and servicing flows around your product lines

Develop and connect to credit bureaus, core banking, and payment systems

Validate against real loan scenarios, launch, then monitor and refine
Whether you’re a mutual replacing a legacy core system or an NBFC scaling up, Sigma can scope the work and give you a timeline in writing, without asking you to compromise on member experience.
RELATED LOCATION
Digital Lending in Sydney
Digital lending platforms for lenders in New South Wales.
RELATED LOCATION
Digital Lending in Brisbane
Digital lending platforms for Victorian lenders.
PLATFORM
Digital Lending in Adelaide
Digital lending platforms for South Australian lenders
PLATFORM
Digital Lending in Melbourne
Digital lending platforms for Western Australian lenders.
Does Sigma build custom loan origination systems, or only implement existing platforms?
Both. We build custom LOS platforms from the ground up and also implement, integrate, or extend existing systems, depending on your credit policy and timeline.
Can you help us prepare for the Consumer Data Right (CDR) obligations for non-bank lenders?
Yes. Non-bank lenders are being brought into the CDR regime from July 2026, with consumer data sharing phasing in through November 2026. We build the API layer and data infrastructure needed to share product and consumer data in the required format.
Can your underwriting logic account for cyclical, resources-linked income?
Yes. We build configurable rules engines and scoring models that can account for variable and cyclical income patterns common among WA borrowers linked to the resources sector, rather than applying a generic scoring model.
Does Sigma have an office in Perth?
Our Australian office is in Baulkham Hills, NSW. WA is a three-hour time zone gap from that office, and we structure delivery and support hours to account for it. In-person meetings are available on request.
How does Sigma handle NCCP responsible lending requirements in the platforms you build?
We build the inquiry, verification, and suitability assessment steps required under the National Consumer Credit Protection Act directly into the origination and underwriting workflow, aligned to ASIC’s RG 209 guidance.
Can you integrate our lending platform with credit bureaus and core banking systems?
Yes. We build API-first integrations with credit bureaus, core banking platforms, payment gateways, and CRMs including Salesforce.
Do you build platforms for equipment and asset finance lenders specifically?
Yes. Given how much of WA’s commercial lending activity ties to mining services, construction, and transport equipment, we build underwriting and servicing workflows suited to asset-backed lending, not just consumer credit.
What security certifications does Sigma hold?
ISO 9001:2015 for quality management and ISO 27001:2022 for information security, along with AWS Select Technology Partner status.
Please fill the form or send us an email at sales@sigmainfo.net